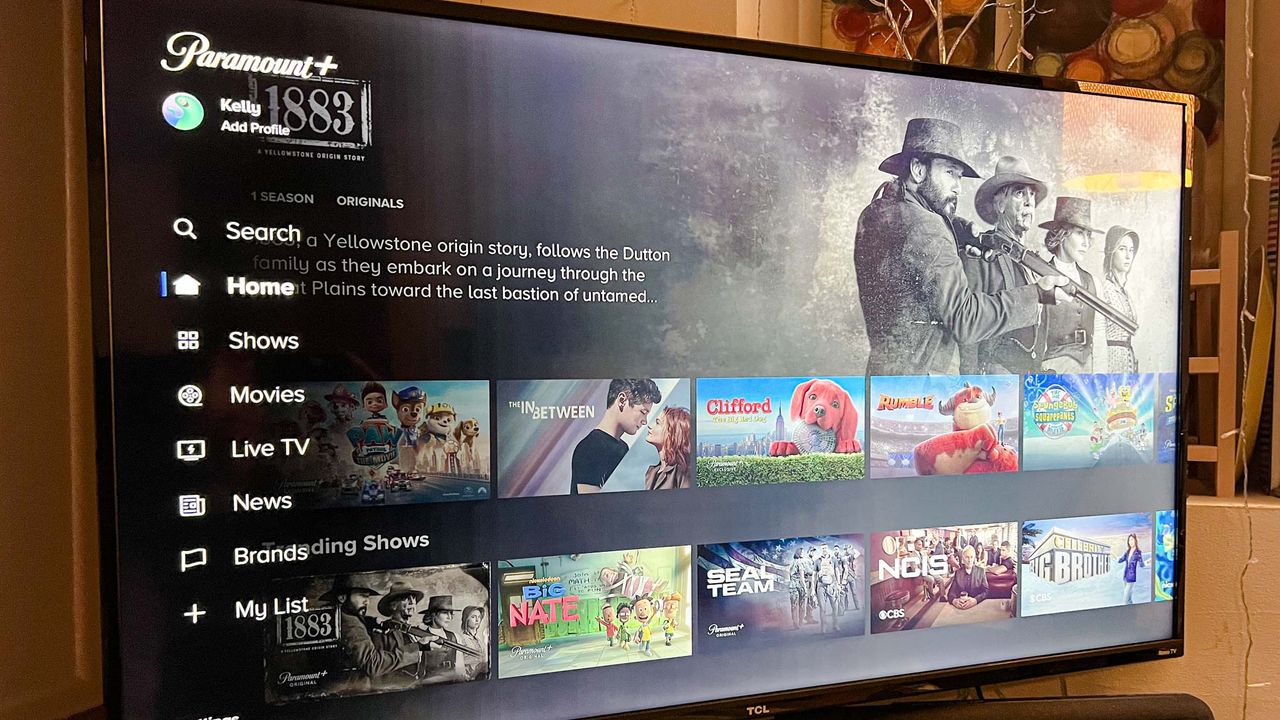
A New Era for Paramount+
2026 has been a pivotal year for Paramount. Following the acquisition by Skydance Media last August, the company has pivoted toward a aggressive strategy to modernize its digital presence. CEO David Ellison has made upgrading the streaming architecture a top priority, aiming to bridge the gap between Paramount+ and its FAST counterpart, Pluto TV.
The goal is simple: consolidate the technology stack to reduce overhead costs while simultaneously scaling the user experience. But with price hikes implemented across the board in early 2026, subscribers are rightfully asking: what exactly am I paying for?
The Numbers Behind the Streamer
Despite the volatility in the broader pay TV industry, Paramount+ has shown resilience. Recent data indicates that streaming revenue grew 17% to $2.17 billion, with Paramount+ driving over 80% of that total. The platform currently boasts more than 79 million subscribers, representing a 14% year-over-year increase.
- Unified technology: Merging tech stacks between Paramount+ and Pluto TV to improve performance.
- AI Integration: Development of new AI tools aimed at deeper personalization and content recommendations.
- Strategic Franchises: Leveraging major IP like 'Star Trek', 'Mission: Impossible', 'Transformers', and 'SpongeBob SquarePants'.
- Live Sports: Maintaining its competitive edge with NFL on CBS, Champions League, and UFC broadcasts.
Content vs. Cost
While the technology is getting an overhaul, the library remains the platform's primary hook. From procedural staples like 'NCIS' and 'Survivor' to prestige dramas like 'Landman' and '1923', the service aims to capture a broad demographic. However, the decision to raise U.S. subscription prices in January 2026 remains a point of contention for value-focused consumers.
For all the regulatory noise, this deal ultimately comes back to the fundamentals of the entertainment business. Control of premium IP and global distribution maximizes engagement and builds scale that compounds.
— Ed Barton, Research Director at Caretta Research